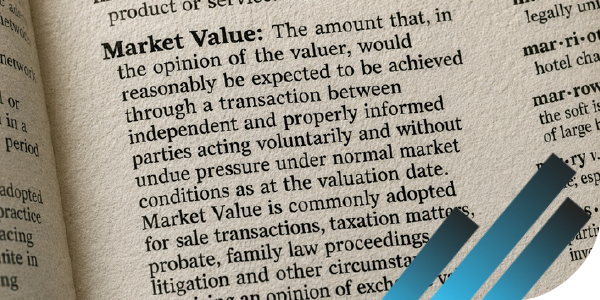
What does market value actually mean? How is it different from insurance value, liquidation value or an auction appraisal? While these terms are used every day by valuers, accountants, lawyers, insurers, financiers and government agencies, Australia has never had a nationally recognised professional standard that brings these definitions together within a single framework for specialist physical asset valuations. That is now changing.
Whether a valuation is prepared for the Australian Taxation Office (ATO), the courts, an insurer, a financier or a private client, one question sits at the heart of every professional opinion, this is what definition of value is actually being applied? The answer has significant legal and financial consequences, making nationally consistent valuation definitions more important than ever.
To address this need, valuers certified by the Auctioneers and Valuers Association of Australia (AVAA) are developing what is expected to become the main nationally recognised professional framework dedicated to valuation definitions and methodology for physical assets. The draft Australian valuation standard, AVAA Professional Standard 17 – Valuation Definitions & Methodology, establishes consistent definitions, recognised valuation methodologies and guiding principles that support professional valuation practice across a wide range of specialist asset classes.
For many years, certified valuers have relied upon a combination of legislation, case law, accounting standards, taxation guidance and international frameworks. While these remain highly important, there has never been a single standard that brings together the commonly used definitions of value and explains when each should appropriately be applied. The result has sometimes been inconsistent terminology, misunderstanding between parties and unnecessary disputes.
The new standard addresses this challenge by defining commonly used concepts including Market Value, Insurance Value, Fair Value, Auction Appraisal Value, Investment Value, Liquidation Value and Scrap Value, while also providing guidance on recognised valuation methodologies and the role of professional judgement. Rather than prescribing a single approach, the framework recognises that the appropriate basis of value depends entirely upon the purpose of the valuation engagement.
This distinction is particularly important where valuations are prepared for taxation purposes. The ATO relies upon market value in numerous contexts, including capital gains tax, deceased estates, cultural gifts, business transactions and other taxation matters. Equally, courts and tribunals require valuation reports that clearly identify both the basis of value adopted and the methodology supporting the conclusion. A valuation prepared for insurance replacement, for example, serves an entirely different purpose from one prepared for taxation or litigation.
The AVAA Professional Standard also addresses increasingly important professional issues including retrospective valuations, thin markets, specialised assets, valuation uncertainty, reconciliation between different methodologies and the appropriate use of specialist advice. These principles are particularly relevant for valuers working with fine art, antiques, Indigenous cultural material, rare books, coins, banknotes, jewellery, collectables, motor vehicles, machinery, marine assets and other specialist property where market evidence may be limited.
Importantly, the development of AVAA Professional Standard 17 – Valuation Definitions & Methodology is being driven by experienced practitioners who hold the respected AVAA Certified Valuer (CVAu) credential. Drawing upon practical experience across Australia’s diverse valuation professions, these certified valuers are developing a framework designed to strengthen consistency while preserving the professional judgement that remains fundamental to competent valuation practice.
The objective is straightforward as professional valuation is not simply about estimating a figure. It is about selecting the correct basis of value, applying recognised methodology, analysing appropriate market evidence and clearly explaining the reasoning that supports the conclusion. Those principles are fundamental to producing valuation reports that withstand scrutiny from clients, government agencies, accountants, lawyers, insurers and the courts.
As Australia’s valuation profession continues to evolve, nationally recognised valuation definitions represent an important step towards greater consistency, stronger professional standards and increased confidence in valuation reports. Through the leadership of those with the respected AVAA Certified Valuer (CVAu) credential, this work is helping establish a common professional language that will benefit valuers, regulators, the Australian Taxation Office and the wider legal and commercial community for years to come.
.
.
Interested In Finding Out More?
If you’re interested in the development of the AVAA Professional Standards, send an email to standards@avaa.co.au or telephone 1300 928 165. You can also stay up to date by following AVAA on LinkedIn, X/Twitter and Facebook.
.